2026-10-13 · Dr. NoVo
Dr. NoVo · Pre-Market Primer
NoVo's lean · BEARISH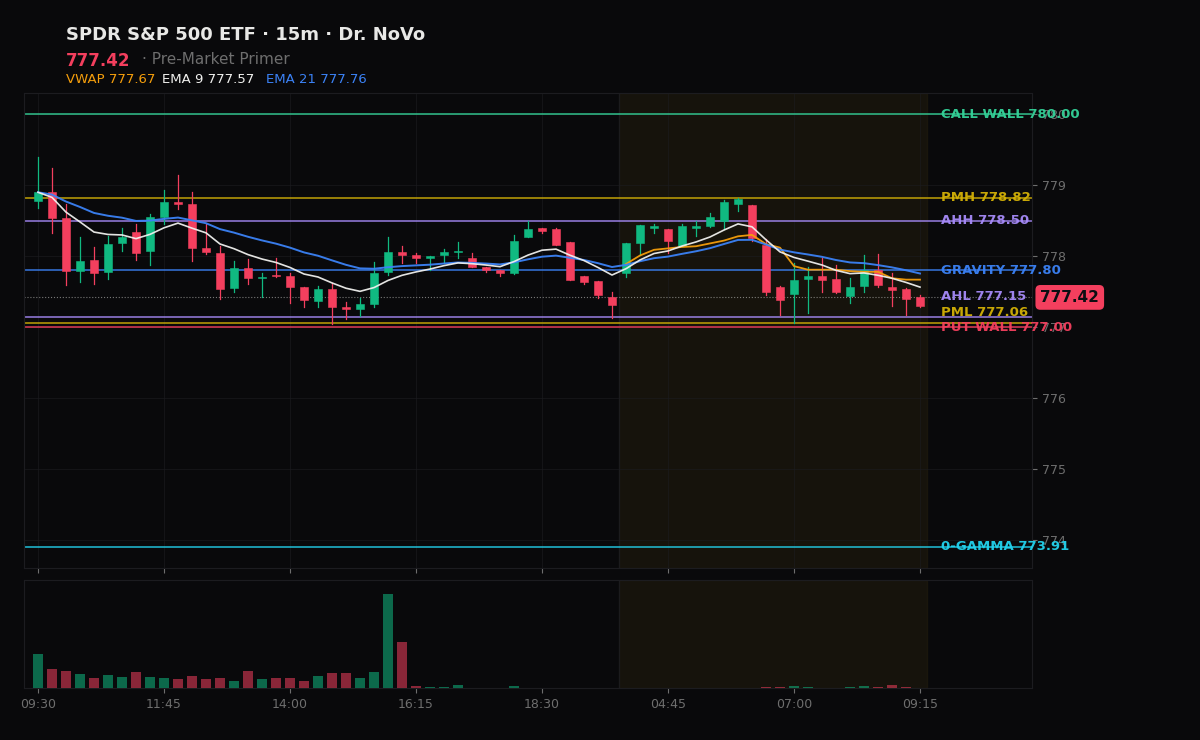
BOTTOM LINE: Equities face a structurally split cash open where positive dealer gamma cushions large caps and small caps, but negative gamma in tech leaves the complex vulnerable to downside acceleration if early support cracks.
THE SETUP
Index futures spent the overnight session compressing inside a narrow balance, holding above Asian session lows while easing Treasury yields and softer crude oil prices provide a modest valuation buffer ahead of tomorrow's September CPI release and the initial wave of Q3 bank earnings. On Hyperliquid, the S&P 500 perp has the market -0.11% since Monday's close, while the Nasdaq 100 perp has it -0.80%, dragged lower by TSLA (-1.26%), META (-1.13%), and NVDA (-1.12%) despite green prints from AAPL (+0.60%), MSFT (+0.56%), and GOOGL (+0.36%). There is no liquid small-cap perp, so offshore flow offers no direct read on IWM, leaving early equity discovery rotational rather than trend-driven.
DEALER POSITIONING
The three index ETFs diverge sharply by dealer regime: SPY and IWM sit in positive gamma, where market makers are forced to buy weakness and sell strength, a posture that dampens realized volatility and encourages mean-reverting chop. In stark contrast, QQQ operates in negative dealer gamma, where hedging mechanics amplify directional momentum by forcing dealers to sell into drops and buy into rips. The aggregate options book retains a net-long delta tilt with steady daily theta decay, but tech's amplifying posture acts as a drag on broad performance, meaning any sharp selloff in QQQ risks overwhelming the dampening buffers on SPY and IWM.
LEVELS TO WATCH
For SPY, holding pre-market support at 777.06 and yesterday's low at 777.05 keeps price stable and preserves the mean-reverting bid toward resistance at the 778.50 after-hours high and the 778.82 pre-market high. A sustained break beneath 777.05 invalidates the stabilizing posture, signaling that negative-gamma selling in QQQ is spilling into broad cash equities and pulling IWM beneath its floor.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 15.3 — 17th percentile of the past year (low vol).
SPY $777.37
Net GEX: +$1.3B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $773.91
Gravity (magnet): $777.80
Call Wall: $780.00 Put Wall: $777.00
Historically (this setup): resolved down 61% of the next hour · median -0.035% · n=428 across 15 sessions
Same structure, next SESSION: resolved up 62% · median +0.194% · n=39 sessions (reconstructed, 2008 on)
Expected move: ±$7.89 (±1.0%) today · ±$17.63 (±2.3%) this week · from quotes outside option hours
Put/Call skew: +1.1 vol pts · roughly balanced
MM skew · 0DTE +1.1 / next +1.1 vol pts · front term structure flat
ATM IV: 16.1% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers BOUGHT 858K SPY shares (~$667.2M) 2026-10-12 final · 0DTE +293K · signed 100% of 6.9M contracts
QQQ $740.33
Net GEX: -$459M · negative — dealers amplify moves (moves extend)
Gamma Flip: $741.65
Gravity (magnet): $744.00
Call Wall: $748.00 Put Wall: $740.00
Historically (this setup): resolved up 77% of the next hour · median +0.081% · n=382 across 7 sessions
Same structure, next SESSION: resolved down 50% · median -0.007% · n=391 sessions (reconstructed, 2008 on)
Expected move: ±$7.18 (±1.0%) today · ±$21.73 (±2.9%) this week · from quotes outside option hours
Put/Call skew: +2.0 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.0 / next +1.9 vol pts · front term structure flat
ATM IV: 15.4% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers BOUGHT 3.1M QQQ shares (~$2.3B) 2026-10-12 final · 0DTE +3.0M · signed 100% of 4.8M contracts
IWM $277.96
Net GEX: +$232M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $275.78
Gravity (magnet): $279.67
Call Wall: $279.00 Put Wall: $277.00
Historically (this setup): resolved down 52% of the next hour · median -0.007% · n=2112 across 18 sessions
Same structure, next SESSION: resolved up 51% · median +0.035% · n=51 sessions (reconstructed, 2008 on)
Expected move: ±$2.56 (±0.9%) today · ±$7.89 (±2.8%) this week · from quotes outside option hours
Put/Call skew: +0.9 vol pts · roughly balanced
MM skew · 0DTE +0.9 / next +0.4 vol pts · 0DTE fear building vs the next expiry
ATM IV: 14.6% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers SOLD 129K IWM shares (~$35.9M) 2026-10-12 final · 0DTE -325K · signed 100% of 524K contracts
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — as today's options decay, dealer delta drifts toward the walls: a mild pull into the close (the pin). Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
Key Levels