2026-09-16 · NoVo Analyst
NoVo Analyst · Pre-Market Primer
NoVo's lean · BULLISH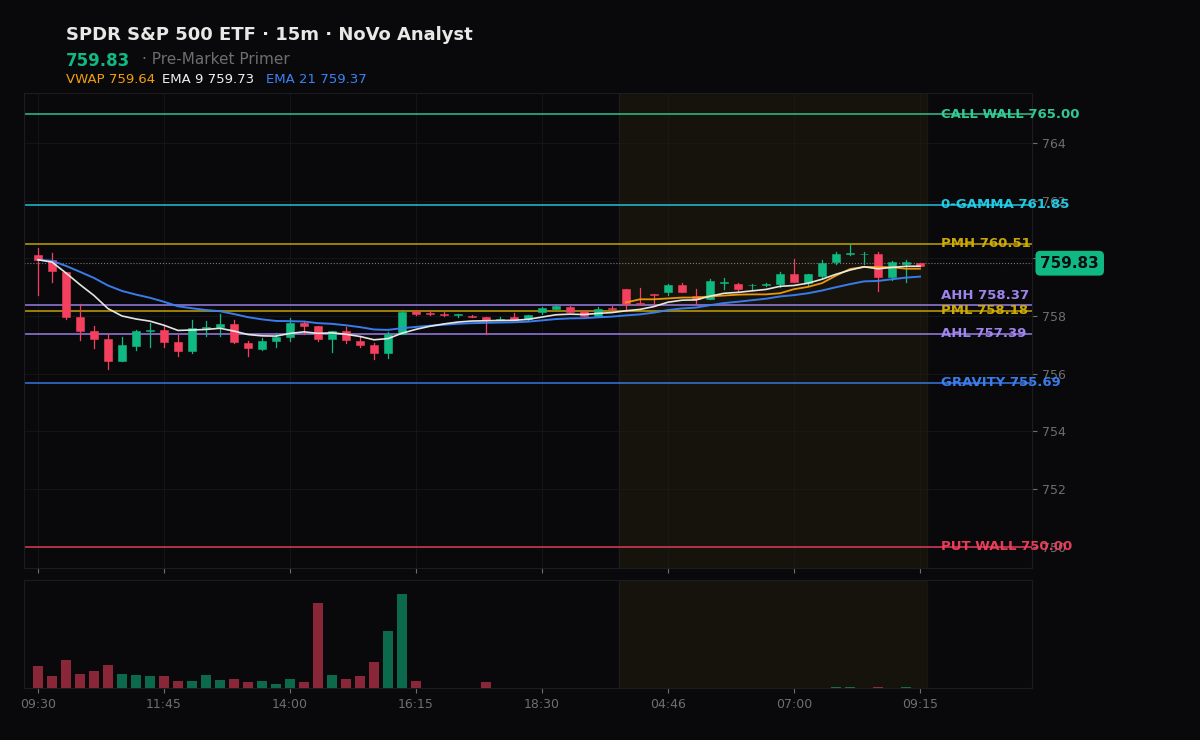
BOTTOM LINE: Equities enter Wednesday in a short-gamma, dealer-amplified posture as futures edge higher into the afternoon FOMC rate decision.
THE SETUP
Index futures are showing a mild pre-market bid, with the S&P 500 contract holding a higher-low structure above overnight session VWAP. The backdrop is dominated by the afternoon FOMC interest rate announcement, where markets are heavily discounting a 25-basis-point rate hike following hotter-than-expected August CPI data. While a modest pullback in 10-year Treasury yields below 5.0% and crude easing near $100 per barrel offer short-term relief, trading conditions before the Fed statement are likely to remain localized and choppy as participants avoid heavy directional commitment.
DEALER POSITIONING
Market makers across SPY ($759.83), QQQ ($708.25), and IWM ($285.81) sit in negative net GEX, establishing a structural regime where dealer hedging amplifies price moves rather than suppressing them. Because spot prices across the board remain below overhead gamma-flip thresholds, market makers are mechanically obligated to sell futures when spot weakens and buy as it rebounds, extending intraday legs in the direction of the trend. The three benchmarks agree on this lack of volatility damping, but diverge in relative vulnerability: QQQ carries heavier downside put-bidding skew to hedge high-duration tech, while small-cap IWM presents a thinner order book that leaves it susceptible to sharp yield-driven moves. Across the options chain, options open interest shows a net-short delta tilt alongside relentless daily theta decay, penalizing static positions that lack immediate momentum.
LEVELS TO WATCH
For SPY ($759.83), upside resistance rests at $760.34 (yesterday's high) and $760.51 (pre-market high); clearing these targets is required to target lower-volatility upside conditions. Downside support sits at $758.18 (pre-market low), $757.39 (after-hours low), and $756.15 (yesterday's low). A sustained 15-minute breakdown beneath $758.18 threatens a short-gamma acceleration leg toward lower liquidity pools ahead of the Fed rate decision.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 16.8 — 42nd percentile of the past year (normal vol).
SPY $759.75
Net GEX: -$245M · negative — dealers amplify moves (moves extend)
Gamma Flip: $761.85
Gravity (magnet): $755.69
Call Wall: $765.00 Put Wall: $750.00
Historically (this setup): resolved up 76% of the next hour · median +0.136% · n=177 across 9 sessions
Same structure, next SESSION: resolved up 55% · median +0.108% · n=597 sessions (reconstructed, 2008 on)
Expected move: ±$16.68 (±2.2%) today · ±$37.29 (±4.9%) this week
Put/Call skew: +5.5 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +5.5 / next +4.6 vol pts · 0DTE fear building vs the next expiry
ATM IV: 34.8%
Off-exchange short volume: 62.0% · 82nd pct of 120d · heavier than usual
QQQ $708.32
Net GEX: -$255M · negative — dealers amplify moves (moves extend)
Gamma Flip: $710.11
Gravity (magnet): $702.09
Call Wall: $715.00 Put Wall: $700.00
Historically (this setup): resolved down 66% of the next hour · median -0.092% · n=428 across 8 sessions
Same structure, next SESSION: resolved down 53% · median -0.032% · n=58 sessions (reconstructed, 2008 on)
Expected move: ±$10.39 (±1.5%) today · ±$23.23 (±3.3%) this week
Put/Call skew: +4.3 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +4.3 / next +4.9 vol pts · 0DTE complacency vs the next expiry
ATM IV: 23.3%
Off-exchange short volume: 65.1% · 61st pct of 120d · typical
Scheduled event: COST reports after close on 2026-09-24 · widens the band, says nothing about direction
IWM $285.81
Net GEX: -$249M · negative — dealers amplify moves (moves extend)
Gamma Flip: $291.36
Gravity (magnet): $282.17
Call Wall: $293.00 Put Wall: $281.00
Historically (this setup): resolved down 52% of the next hour · median -0.007% · n=2853 across 14 sessions
Same structure, next SESSION: resolved up 55% · median +0.157% · n=1001 sessions (reconstructed, 2008 on)
Expected move: ±$5.65 (±2.0%) today · ±$12.64 (±4.4%) this week
Put/Call skew: +3.9 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +3.9 / next +4.4 vol pts · 0DTE complacency vs the next expiry
ATM IV: 31.4%
Off-exchange short volume: 60.4% · 39th pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — in a negative-gamma regime, decay doesn't pin; moves can extend into the close. Vanna — with dealers short gamma, a drop in vol would ease the amplification and let the tape settle. Second-order dealer flow context.
Key Levels
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus real-time ‘The Line’ level-break alerts in Discord.
Start a 7-day free trial →