2026-08-12 · NoVo Analyst
NoVo Analyst · Pre-Market Primer
Structural Bias · BULLISH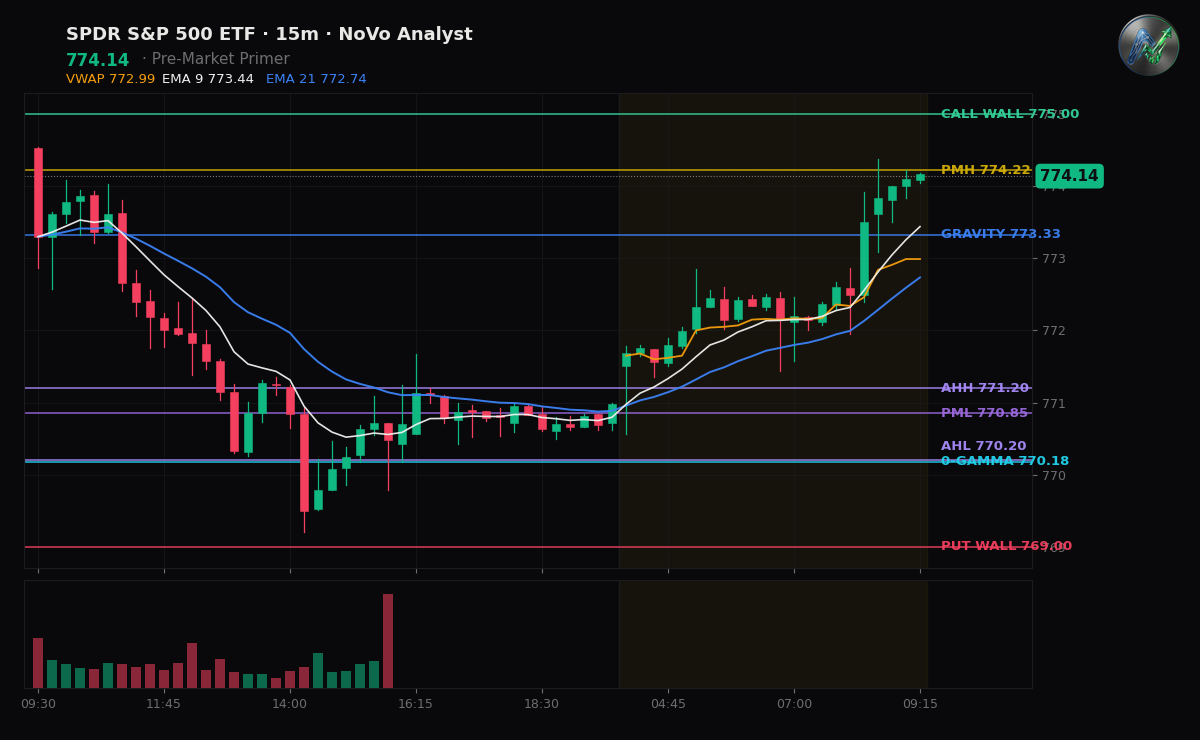
BOTTOM LINE: Equities enter the bell with a bullish pre-market gap as in-line CPI relief fuels broad-market upside, though sticky crude prices keep the advance measured.
THE SETUP
Index futures hold a firm pre-market bid following an aggressive 08:30 AM EST breakout, pushing SPY ($774.14) up +0.47% vs the prior close alongside strength in QQQ ($725.83) and IWM ($302.90). This morning's July Consumer Price Index print provided critical macro relief, showing headline inflation cooling to 3.4% year-over-year while core CPI eased to 2.5%—both matching consensus expectations and solidifying rate-cut bets following July's nonfarm payroll contraction. However, ongoing geopolitical friction in the Middle East continues to anchor crude oil near $90 a barrel, preserving a baseline of volatility. Expect an expansive open where buyers test overhead supply, but structural resistance limits unhedged runaway momentum.
DEALER POSITIONING
Market maker posture across the index complex reflects structural stability. For SPY, net GEX sits in positive territory at +$0.7B, obligating dealers to act as shock absorbers by buying dips and selling rallies—a dynamic that dampens volatility and enforces mean-reversion. QQQ and IWM share this positive net-gamma cushion, creating broad-based resistance against sudden intraday cascades. Despite the spot gap, index alignment displays a minor divergence: tech flow in QQQ exhibits higher sensitivity to rate-cut chatter, whereas small-cap IWM trades nearer to its gamma-flip pivot, making its trend fragile if early momentum stalls. Across the public options book, standing positioning holds a net-short delta tilt (~-0.3M delta-equivalent) alongside ~$8.8M in daily theta decay, creating a continuous cost drag on long contract holders into the session.
LEVELS TO WATCH
For SPY, defending immediate pre-market support at $770.85 (PM low) and yesterday's low at $769.34 is essential to maintain this morning's bullish posture. Clearing overhead resistance at $774.22 (PM high) and yesterday's high at $774.61 opens a path toward broader supply targets. A breakdown below the $770.18 gamma flip would fundamentally shift dealer mechanics from dampening price action to amplifying sell-side volume, accelerating downside exposure toward lower support boundaries. For QQQ and IWM, maintaining trade above their respective positive-gamma floors preserves the broad-market recovery, while a break beneath those pivots would collapse the post-CPI expansion and realign price action with downside risk.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 15.0 — 8th percentile of the past year (very low vol).
SPY $774.15
Net GEX: +$721M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $770.18
Gravity (magnet): $773.33
Call Wall: $775.00 Put Wall: $769.00
Expected move: ±$12.80 (±1.6%) today · ±$28.63 (±3.7%) this week
Put/Call skew: +1.7 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +1.7 / next +0.9 vol pts · 0DTE fear building vs the next expiry
ATM IV: 26.3%
QQQ $725.83
Net GEX: +$187M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $724.76
Gravity (magnet): $718.59
Call Wall: $730.00 Put Wall: $715.00
Expected move: ±$9.41 (±1.3%) today · ±$22.88 (±3.1%) this week
Put/Call skew: +2.1 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.1 / next +2.3 vol pts · front term structure flat
ATM IV: 20.6%
IWM $302.90
Net GEX: +$129M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $301.27
Gravity (magnet): $301.60
Call Wall: $303.00 Put Wall: $298.00
Expected move: ±$4.33 (±1.4%) today · ±$9.69 (±3.2%) this week
Put/Call skew: +2.8 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.8 / next +2.2 vol pts · 0DTE fear building vs the next expiry
ATM IV: 22.7%
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — as today's options decay, dealer delta drifts toward the walls: a mild pull into the close (the pin). Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
Key Levels
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →