2026-09-15 · NoVo Analyst
NoVo Analyst · Pre-Market Primer
NoVo's lean · BEARISH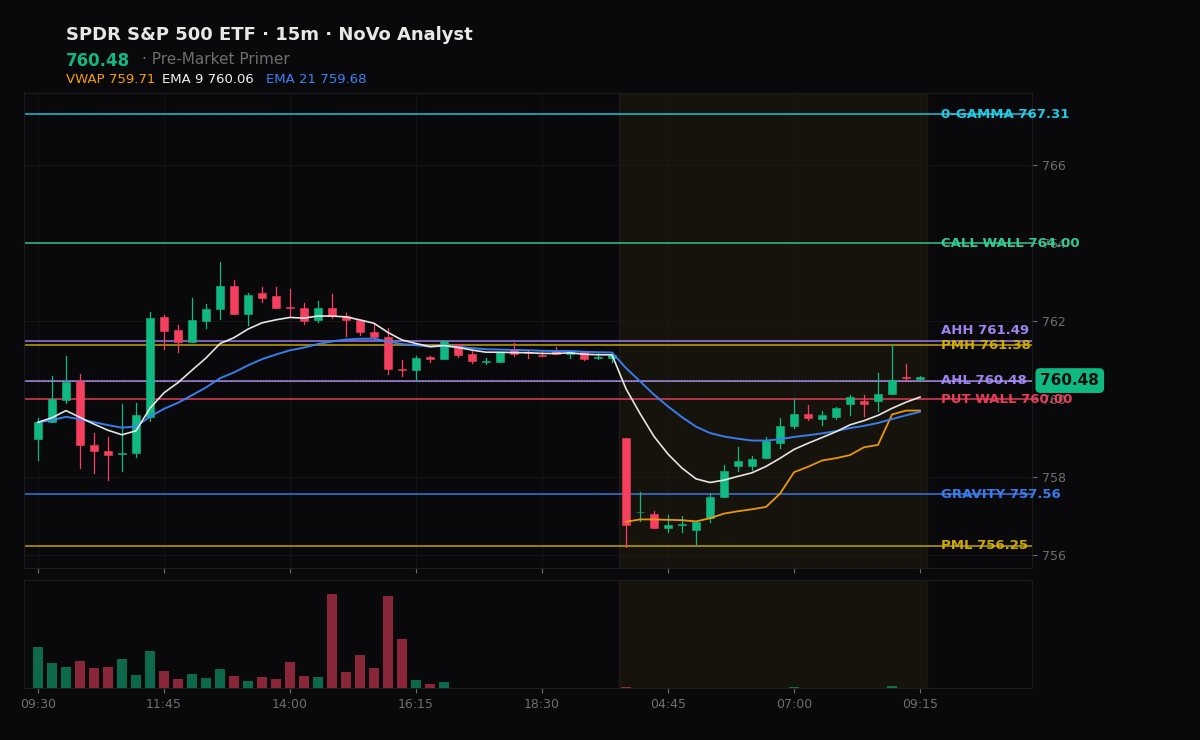
BOTTOM LINE: The index complex opens under severe interest-rate pressure, with negative dealer gamma threatening downside trend acceleration if morning support fails.
THE SETUP
Equities face a challenging open as macro yields hit extreme highs, with the 10-year Treasury yield surging past 5.0% alongside Brent crude holding above $105 per barrel. Markets enter Tuesday pricing in a 92% probability of a 25-basis-point rate hike at Wednesday's FOMC meeting, compounding valuation drag across the equity book. S&P 500 futures spent the overnight session sweeping down to a 7,645.00 low before rebounding toward pre-market high resistance near 7,695.00. While the pre-market tape shows a modest morning bounce, the broader setup favors persistent, supply-driven distribution rather than durable dip-buying until macro yield pressures abate.
DEALER POSITIONING
Dealer mechanics across SPY ($760.48), QQQ ($708.95), and IWM ($286.71) are structurally aligned to amplify price volatility rather than absorb it. Market makers sit in a negative net-gamma regime across all three benchmark ETFs, forcing them to hedge dynamically by selling into market weakness and buying into market strength. The three indices AGREE on a lack of structural damping, but DIVERGE in relative vulnerability: tech-heavy QQQ displays deeper downside put bidding to reflect persistent institutional portfolio hedging, while small-cap IWM remains exceptionally fragile due to its thin liquidity buffer against elevated interest rates. Options book skew shows elevated demand for downside put protection alongside persistent daily theta decay, heavily penalizing static positions that fail to catch immediate momentum.
LEVELS TO WATCH
For SPY ($760.48), primary resistance sits at the pre-market high of $761.38, followed by yesterday's high at $763.52 and the $764.00 call wall. Downside support rests at the $760.00 put wall, followed by the pre-market low of $756.25 and gravity at $757.56. A sustained 15-minute breakdown beneath $756.25 confirms a short-gamma liquidation leg, while a reclaim above $761.38 is required to stabilize the morning tape toward $763.52.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 16.9 — 44th percentile of the past year (normal vol).
SPY $760.57
Net GEX: -$3.1B · negative — dealers amplify moves (moves extend)
Gamma Flip: $767.31
Gravity (magnet): $757.56
Call Wall: $764.00 Put Wall: $760.00
Historically (this setup): resolved up 56% of the next hour · median +0.022% · n=2638 across 12 sessions
Same structure, next SESSION: resolved up 56% · median +0.195% · n=542 sessions (reconstructed, 2008 on)
Expected move: ±$6.80 (±0.9%) today · ±$18.11 (±2.4%) this week
Put/Call skew: +2.3 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.3 / next +3.4 vol pts · 0DTE complacency vs the next expiry
ATM IV: 14.2%
Off-exchange short volume: 43.0% · 9th pct of 120d · lighter than usual
QQQ $708.93
Net GEX: -$1.0B · negative — dealers amplify moves (moves extend)
Gamma Flip: $712.75
Gravity (magnet): $707.89
Call Wall: $715.00 Put Wall: $705.00
Historically (this setup): resolved down 54% of the next hour · median -0.011% · n=2137 across 12 sessions
Same structure, next SESSION: resolved down 53% · median -0.101% · n=68 sessions (reconstructed, 2008 on)
Expected move: ±$7.56 (±1.1%) today · ±$22.02 (±3.1%) this week
Put/Call skew: +2.3 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.3 / next +3.4 vol pts · 0DTE complacency vs the next expiry
ATM IV: 16.9%
Off-exchange short volume: 63.4% · 50th pct of 120d · typical
Scheduled event: COST reports after close on 2026-09-24 · widens the band, says nothing about direction
IWM $286.71
Net GEX: -$147M · negative — dealers amplify moves (moves extend)
Gamma Flip: $289.82
Gravity (magnet): $287.24
Call Wall: $290.00 Put Wall: $286.00
Historically (this setup): resolved down 54% of the next hour · median -0.021% · n=2605 across 14 sessions
Same structure, next SESSION: resolved up 55% · median +0.170% · n=1009 sessions (reconstructed, 2008 on)
Expected move: ±$2.91 (±1.0%) today · ±$8.46 (±3.0%) this week
Put/Call skew: +2.2 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +2.2 / next +2.8 vol pts · 0DTE complacency vs the next expiry
ATM IV: 16.1%
Off-exchange short volume: 58.3% · 32nd pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — in a negative-gamma regime, decay doesn't pin; moves can extend into the close. Vanna — with dealers short gamma, a drop in vol would ease the amplification and let the tape settle. Second-order dealer flow context.
Key Levels
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →