2026-09-22 · NoVo Analyst
NoVo Analyst · Pre-Market Primer
NoVo's lean · BULLISH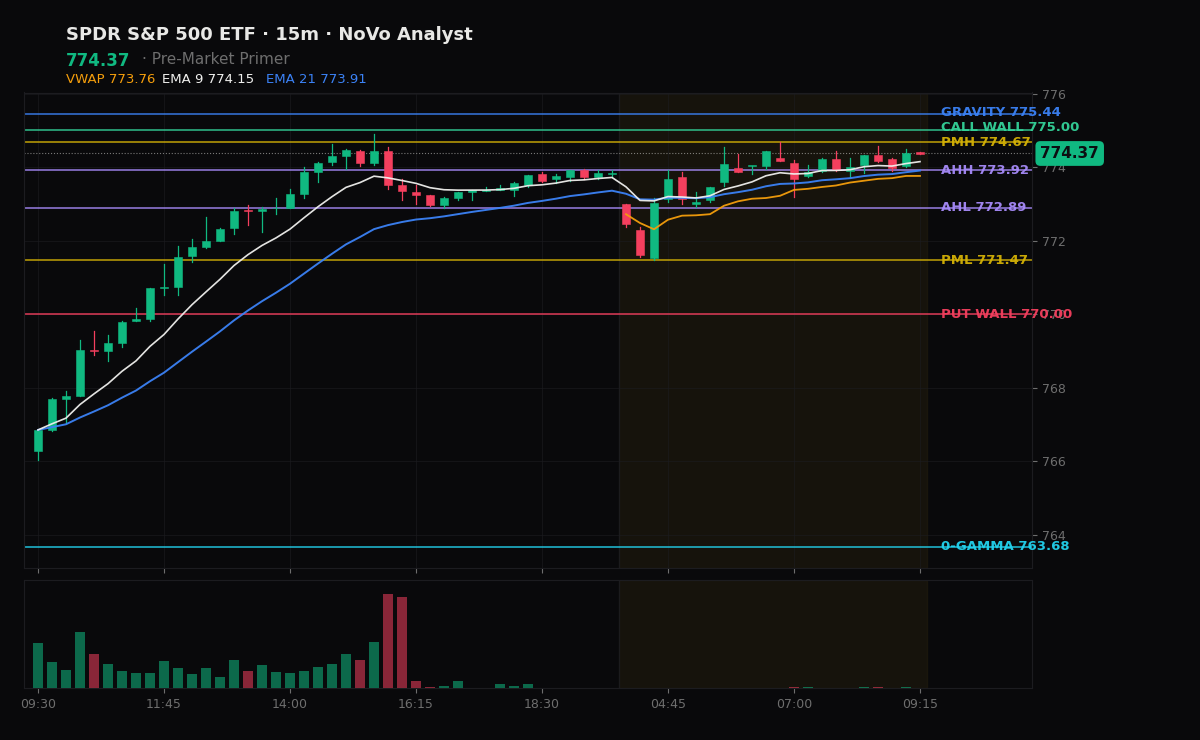
BOTTOM LINE: Index options structure enters the open in a volatility-suppressed hold, pointing to mean-reverting chop unless spot price breaks cleanly past immediate boundaries.
THE SETUP
Spot SPY ($774.37) enters the session with a mild overnight gap up (+0.11%), extending premium above the prior close while S&P 500 futures hold above overnight VWAP (7832.65). Macro sentiment is stabilizing as crude oil prices ease on diplomatic chatter regarding Middle East supply disruptions, counterbalancing hawkish rhetoric from St. Louis Fed President Alberto Musalem, who noted the current 3.75%–4.00% target rate remains "accommodative" following last week's 25-basis-point hike. With front-end volatility suppressed, options time-decay carries a steep daily cost; expecting immediate trend runaway without a fresh catalyst misreads the tape, making orderly rotation within overnight bounds the path of least resistance.
DEALER POSITIONING
Market maker posture across SPY and QQQ operates in a net positive gamma regime, creating a mechanical shock absorber across broad market and megacap equities. In this regime, dealer hedging dampens directional momentum by selling strength toward overhead call walls and buying dips near support, pulling spot back toward central magnets. QQQ matches this volatility-suppressed posture, providing a structural buffer for tech. Conversely, IWM displays clear cross-index divergence by hovering near a net negative gamma posture where short dealer hedging amplifies price extensions; this leaves small caps prone to sharper relative swings than their large-cap peers. Across the broader public options book, standing open interest carries a net-long delta tilt alongside steady daily theta decay, leaving unconfirmed breakout attempts vulnerable to time-value erosion.
LEVELS TO WATCH
For SPY ($774.37), immediate upside resistance sits at the pre-market high of $774.67, with the primary call wall overhead at $775.00 marking the upper structural barrier. Downside support rests at the pre-market low of $771.47, followed by the main put wall at $770.00. A sustained 15-minute close above $775.00 would force market makers to cover short call hedges, unlocking potential upside extension; conversely, a 15-minute close beneath $771.47 invalidates the immediate bullish drift and opens a retracement toward the $770.00 put wall where positive dealer gamma acts to absorb selling pressure.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 14.6 — 6th percentile of the past year (very low vol).
SPY $774.38
Net GEX: +$3.6B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $763.68
Gravity (magnet): $775.44
Call Wall: $775.00 Put Wall: $770.00
Historically (this setup): resolved up 54% of the next hour · median +0.015% · n=2378 across 11 sessions
Same structure, next SESSION: resolved down 51% · median -0.005% · n=258 sessions (reconstructed, 2008 on)
Expected move: ±$9.16 (±1.2%) today · ±$20.49 (±2.6%) this week
Put/Call skew: +0.5 vol pts · roughly balanced
MM skew · 0DTE +0.5 / next +0.3 vol pts · front term structure flat
ATM IV: 18.8%
Off-exchange short volume: 51.0% · 29th pct of 120d · typical
QQQ $741.06
Net GEX: +$1.2B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $737.26
Gravity (magnet): $741.55
Call Wall: $748.00 Put Wall: $735.00
Historically (this setup): resolved up 50% of the next hour · median +0.003% · n=2728 across 15 sessions
Same structure, next SESSION: resolved up 53% · median +0.044% · n=489 sessions (reconstructed, 2008 on)
Expected move: ±$7.63 (±1.0%) today · ±$21.28 (±2.9%) this week
Put/Call skew: +3.0 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +3.0 / next +3.2 vol pts · front term structure flat
ATM IV: 16.4%
Off-exchange short volume: 53.5% · 12th pct of 120d · lighter than usual
Scheduled event: COST reports after close on 2026-09-24 · widens the band, says nothing about direction
IWM $288.14
Net GEX: +$144M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $286.52
Gravity (magnet): $286.89
Call Wall: $290.00 Put Wall: $285.00
Historically (this setup): resolved up 57% of the next hour · median +0.026% · n=2062 across 8 sessions
Same structure, next SESSION: resolved down 55% · median -0.048% · n=137 sessions (reconstructed, 2008 on)
Expected move: ±$2.92 (±1.0%) today · ±$7.68 (±2.7%) this week
Put/Call skew: +0.5 vol pts · roughly balanced
MM skew · 0DTE +0.5 / next +1.0 vol pts · 0DTE complacency vs the next expiry
ATM IV: 16.1%
Off-exchange short volume: 66.5% · 65th pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — as today's options decay, dealer delta drifts toward the walls: a mild pull into the close (the pin). Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
Key Levels
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →