2026-09-25 · NoVo Analyst
NoVo Analyst · Pre-Market Primer
NoVo's lean · BULLISH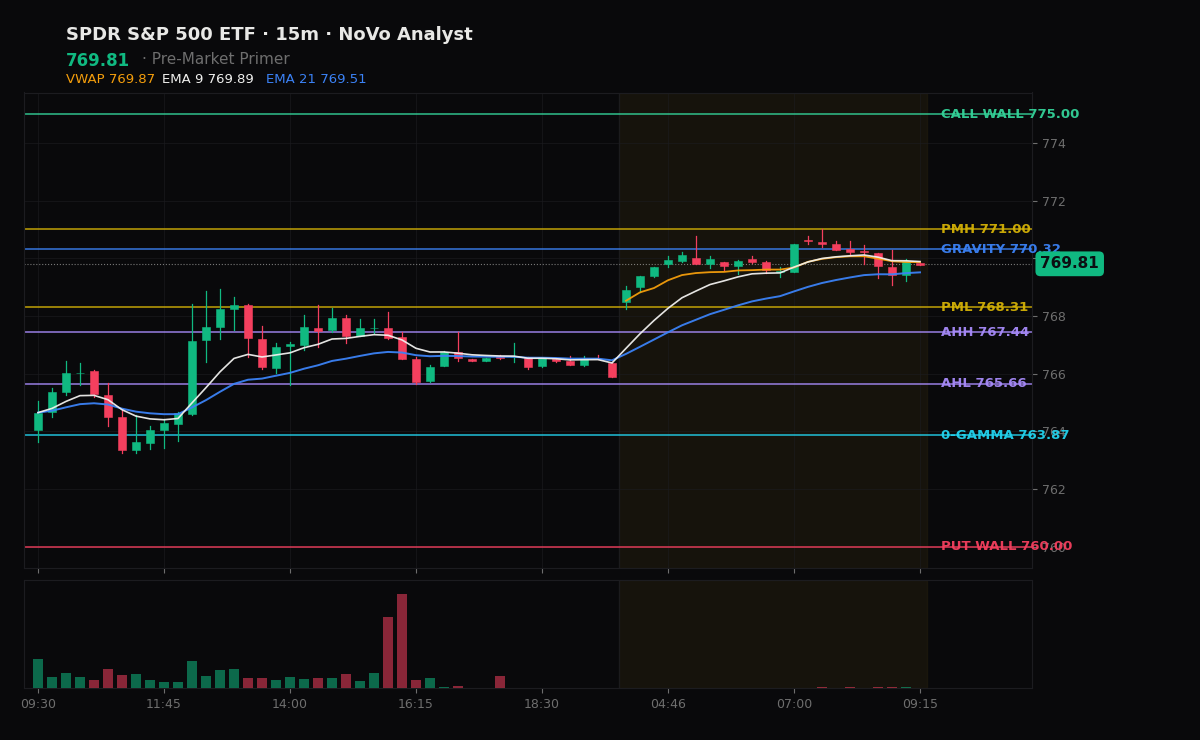
BOTTOM LINE: Equity futures are mounting a modest pre-market recovery as a pullback in crude oil offsets persistent long-end Treasury yield pressure, setting up a stabilizing open within a high-gamma, mean-reverting environment.
THE SETUP
S&P 500 futures extend their overnight recovery from early Asian session lows of 7748.50, sweeping through the London session high to test resistance near 7800.75. Long-end Treasury yields remain a core valuation drag, with the 10-year Treasury yield easing slightly to 5.18% after crossing multi-decade highs above 5.20% following a hot 58.4 composite PMI print earlier in the week. However, equity valuations are getting tactical breathing room as WTI crude contracts pull back toward $95 a barrel following reports of indirect diplomatic talks between Washington and Tehran at the UN General Assembly. With overnight price holding above session VWAP, the open leans toward orderly balance rather than directional trend expansion, making early range breakouts vulnerable to mean-reversion fades.
DEALER POSITIONING
Across the index complex, market maker hedging posture shows a clear split between stabilizing broad market liquidity and move-amplifying posture in tech and small caps. Broad market SPY positioning sits in positive gamma territory, meaning dealers are mechanically required to sell into strength and buy into dips, dampening intraday range expansion. Tech-heavy QQQ and small-cap IWM carry net-negative dealer gamma postures, keeping them vulnerable to momentum extension if key levels break. Options order flow displays downside put skew across QQQ as tech traders maintain tail-risk hedges against persistent discount-rate expansion, while IWM exhibits a relatively balanced skew posture. Net-short delta across the standing options chain means sideways chop will systematically erode option premiums via theta decay.
LEVELS TO WATCH
For SPY ($769.81), upside resistance sits at the pre-market high of $771.00, followed by the call wall at $775.00. Downside support holds at the pre-market low of $768.31, followed by the prior-day low of $763.25. The structural read flips if spot breaks and holds below the gamma flip level of $763.87; a 15-minute close below that threshold converts dealer posture from move-dampening to short-gamma acceleration, shifting the tape into a trend-down regime. For QQQ ($744.72) and IWM ($282.52), sustaining price above their respective opening range VWAPs is required to keep tech and small-cap books from slipping back into downside dealer hedging cascades.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 15.1 — 12th percentile of the past year (very low vol).
SPY $769.85
Net GEX: +$3.8B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $763.87
Gravity (magnet): $770.32
Call Wall: $775.00 Put Wall: $760.00
Historically (this setup): resolved up 54% of the next hour · median +0.013% · n=2669 across 13 sessions
Same structure, next SESSION: resolved down 51% · median -0.006% · n=257 sessions (reconstructed, 2008 on)
Expected move: ±$10.90 (±1.4%) today · ±$24.37 (±3.2%) this week
Put/Call skew: +1.2 vol pts · roughly balanced
MM skew · 0DTE +1.2 / next +0.9 vol pts · 0DTE fear building vs the next expiry
ATM IV: 22.5%
Off-exchange short volume: 46.6% · 13th pct of 120d · lighter than usual
QQQ $744.63
Net GEX: +$876M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $743.21
Gravity (magnet): $741.05
Call Wall: $746.00 Put Wall: $736.00
Historically (this setup): resolved up 58% of the next hour · median +0.033% · n=575 across 9 sessions
Same structure, next SESSION: resolved up 52% · median +0.048% · n=518 sessions (reconstructed, 2008 on)
Expected move: ±$8.14 (±1.1%) today · ±$22.28 (±3.0%) this week
Put/Call skew: +1.5 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +1.5 / next +1.7 vol pts · front term structure flat
ATM IV: 17.3%
Off-exchange short volume: 53.8% · 13th pct of 120d · lighter than usual
IWM $282.52
Net GEX: -$19M · negative — dealers amplify moves (moves extend)
Gamma Flip: $282.62
Gravity (magnet): $282.18
Call Wall: $287.00 Put Wall: $280.00
Same structure, next SESSION: resolved up 50% · median +0.032% · n=494 sessions (reconstructed, 2008 on)
Expected move: ±$3.83 (±1.4%) today · ±$8.57 (±3.0%) this week
Put/Call skew: -0.3 vol pts · roughly balanced
MM skew · 0DTE -0.3 / next +0.3 vol pts · 0DTE complacency vs the next expiry
ATM IV: 21.5%
Off-exchange short volume: 67.4% · 68th pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — as today's options decay, dealer delta drifts toward the walls: a mild pull into the close (the pin). Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
Key Levels
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →