2026-09-27 · NoVo Analyst
NoVo · The Week Ahead
Structural Bias · NEUTRAL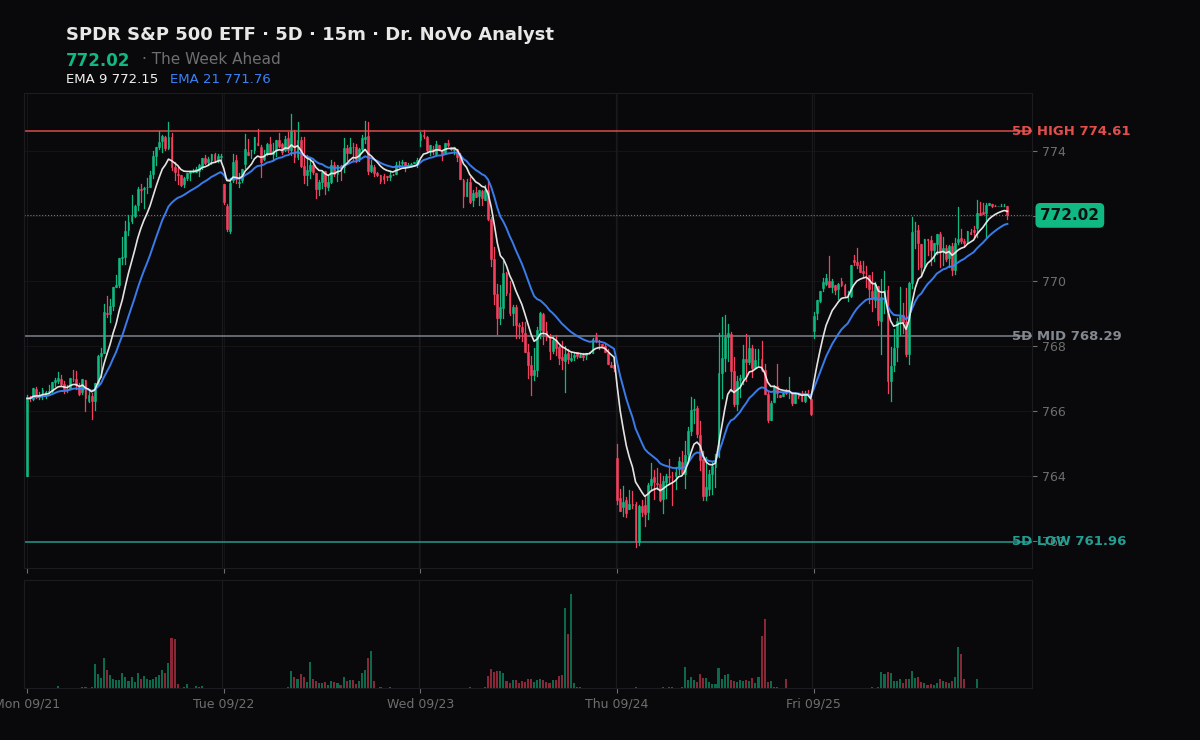
BOTTOM LINE: The index complex opens the catalyst-heavy week in a synchronized positive-gamma hold, where dealer hedging will dampen intraday swings unless persistent yield pressure or tier-one economic prints force spot price through key structural support.
THE WEEK AHEAD
The multi-day picture across the index complex reflects structural stabilization above key structural floors, but underlying momentum remains tightly constrained by macro discount-rate pressures. S&P 500 futures hold overnight trade above session VWAP targets, keeping SPY ($772.02) pinned near its weekly gravity level while QQQ ($745.33) and IWM ($282.26) maintain synchronized alignments above their structural gamma flips. Broad equities and tech continue to demonstrate relative resilience against elevated 10-year Treasury yields hovering near 5.17%, whereas small-cap IWM remains the structural laggard due to its heightened balance-sheet sensitivity to persistent higher-for-longer monetary policy. All three major index ETFs sit in positive dealer gamma regimes, meaning market makers are structurally positioned to buy dips and sell rallies—a dynamic that suppresses broad-market volatility and forces price into tight consolidation. A sustained break below the index gamma flips would dismantle this mean-reverting environment, shifting market-maker hedging from move-dampening to move-amplifying posture and opening the door for accelerated directional expansion.
CATALYSTS
Macro volatility is scheduled to build progressively through the session calendar, testing whether equity valuations can withstand elevated discount rates.
* **Monday, September 28:** The Dallas Fed Manufacturing Index (10:30 AM ET) and remarks from Fed Governor Michael Barr (9:05 AM ET) set the early operational tone, alongside after-hours earnings from Jefferies and Vail Resorts.
* **Tuesday, September 29:** Labor market fluidity comes into focus with JOLTS Job Openings (10:00 AM ET) and CB Consumer Confidence (10:00 AM ET), accompanied by a heavy slate of Fed speakers including Vice Chair Michelle Bowman (11:00 AM ET) and Governors Barr (12:40 PM ET) and Christopher Waller (3:00 PM ET).
* **Wednesday, September 30:** A dense catalyst morning brings ADP Employment Change (8:15 AM ET), Personal Income & Outlays alongside PCE & Core PCE Price Index data (8:30 AM ET), and the Final Q2 GDP estimate (8:30 AM ET), followed by Pending Home Sales (10:00 AM ET) and earnings from Micron Technology after the bell.
* **Thursday, October 1:** Initial Jobless Claims (8:30 AM ET) and ISM Manufacturing PMI (10:00 AM ET) measure broader economic momentum, with Nike reporting earnings post-close.
* **Friday, October 2:** The marquee event of the week arrives with the September Nonfarm Payrolls, Unemployment Rate, and Average Hourly Earnings report (8:30 AM ET), which will directly reprice rate expectations heading into the fourth quarter.
SCENARIOS
The options market prices an expected weekly range of ±$16.15 for SPY, ±$21.87 for QQQ, and ±$7.93 for IWM. For SPY, upper resistance stands at $772.46, followed by the $780.00 call wall; immediate support holds at $771.10, followed by $766.29 and the $763.00 put wall.
* **Base Case (Range-Bound Hold):** Spot price rotates inside the expected weekly band as positive dealer gamma absorbs directional flow. Under this condition, rallies toward the $780.00 call wall on SPY and equivalent upper resistance on QQQ stall, while pullbacks toward $770.31 find steady dealer buy-side hedging.
* **Bull Case (Topside Expansion):** A cool Core PCE print on Wednesday followed by benign labor data drives a yield pullback, pushing SPY above $772.46. A 15-minute close above $772.46 triggers momentum buying toward the $780.00 call wall, forcing short-call covering across QQQ and IWM.
* **Bear Case (Short-Gamma Acceleration):** Hotter-than-expected inflation or employment data drives 10-year yields to new local highs, forcing SPY below its $770.31 gamma flip. A sustained 15-minute close below
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 14.9 — 8th percentile of the past year (very low vol).
SPY $772.02
Net GEX: +$1.1B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $770.31
Gravity (magnet): $772.22
Call Wall: $780.00 Put Wall: $763.00
Historically (this setup): resolved down 52% of the next hour · median -0.012% · n=417 across 10 sessions
Same structure, next SESSION: resolved up 56% · median +0.044% · n=434 sessions (reconstructed, 2008 on)
Expected move (this week): ±$16.17 (±2.1%)
Put/Call skew: +0.7 vol pts · roughly balanced
MM skew · 0DTE +0.7 / next +0.7 vol pts · front term structure flat
ATM IV: 8.0%
Off-exchange short volume: 52.4% · 38th pct of 120d · typical
QQQ $745.33
Net GEX: +$233M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $744.79
Gravity (magnet): $741.04
Call Wall: $749.00 Put Wall: $730.00
Historically (this setup): resolved up 63% of the next hour · median +0.044% · n=218 across 8 sessions
Same structure, next SESSION: resolved up 58% · median +0.112% · n=349 sessions (reconstructed, 2008 on)
Expected move (this week): ±$21.91 (±2.9%)
Put/Call skew: +1.2 vol pts · roughly balanced
MM skew · 0DTE +1.2 / next +1.4 vol pts · front term structure flat
ATM IV: 11.4%
Off-exchange short volume: 57.7% · 29th pct of 120d · typical
IWM $282.26
Net GEX: +$72M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $281.77
Gravity (magnet): $283.77
Call Wall: $287.00 Put Wall: $280.00
Same structure, next SESSION: resolved down 51% · median -0.004% · n=233 sessions (reconstructed, 2008 on)
Expected move (this week): ±$7.91 (±2.8%)
Put/Call skew: +0.0 vol pts · roughly balanced
MM skew · 0DTE +0.0 / next +0.3 vol pts · 0DTE complacency vs the next expiry
ATM IV: 12.4%
Off-exchange short volume: 66.9% · 66th pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — while dealers hold long gamma, each session's options decay pulls their delta toward the walls: a recurring drift into the daily close (the pin) through the week. Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →