2026-10-04 · Dr. NoVo
NoVo · The Week Ahead
Structural Bias · BULLISH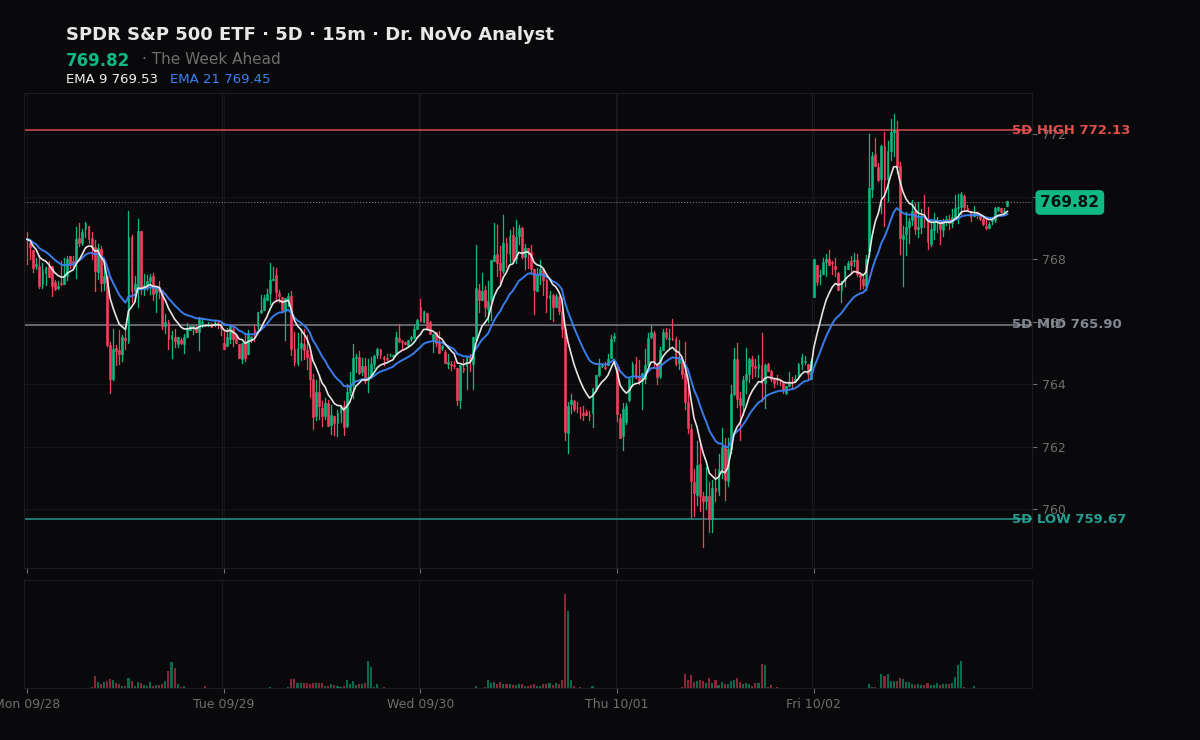
BOTTOM LINE: Equities enter the week pinned in a positive dealer gamma regime across all three indexes, pointing to a dampening, mean-reverting tape unless incoming tier-one macro catalysts trigger a volatility expansion.
THE WEEK AHEAD
Broad equities (SPY $769.82) and tech (QQQ $749.63) sit near the upper boundary of their five-day ranges following Friday's cool labor print, while small caps (IWM $281.69) continue to diverge by lagging off their highs. Market makers sit in positive gamma across SPY, QQQ, and IWM alike; in this regime, dealers mechanically absorb momentum by selling into rallies and buying into dips, which grinds directional thrust into range-bound balance. Over the weekend on Hyperliquid, the S&P 500 perp is +0.14% and the Nasdaq 100 perp is +0.36% above Friday's cash close, carried higher by green prints across mega-caps with TSLA +0.65%, NVDA +0.56%, GOOGL +0.19%, META +0.17%, AMZN +0.13%, and MSFT +0.03% offsetting AAPL -0.15%. This perp pricing reflects a live market price on another venue rather than a cash forecast, and because there is no liquid small-cap perp, it gives no structural read on IWM. Whether the week resolves into a continuation breakout or a reversion slide depends on whether small caps confirm tech's bid or drag the complex lower.
CATALYSTS
Monday leads with S&P Global Final Services PMI at 9:45 AM ET followed by ISM Services PMI at 10:00 AM ET, setting the early growth tone. Tuesday features the U.S. Trade Balance at 8:30 AM ET and remarks from Fed Governor Michelle Bowman at 10:45 AM ET, alongside Constellation Brands reporting after the bell. Wednesday brings the key macro focus with FOMC Meeting Minutes at 2:00 PM ET and NY Fed 1-Year Inflation Expectations at 11:00 AM ET, with Levi Strauss and Applied Digital reporting after hours. Thursday carries Fed Governor Christopher Waller speaking early at 4:30 AM ET, Initial Jobless Claims at 8:30 AM ET, and PepsiCo earnings before the open. Friday rounds out the slate with Preliminary University of Michigan Consumer Sentiment at 10:00 AM ET and Delta Air Lines earnings before the bell.
SCENARIOS
The broad market enters the week bounded by SPY support at 768.99 and 767.14, with resistance standing at 770.16 and 772.65.
* Base Case: Price remains trapped between SPY support at 768.99 and resistance at 770.16 as positive dealer gamma across SPY, QQQ, and IWM compresses intraday moves into two-sided mean reversion around Friday's value area.
* Bull Case: A sustained cash push clearing SPY 770.16 and 772.65 forces tech continuation and pulls IWM off its lows, neutralizing dealer dampening and exposing an extension toward broader upside targets.
* Bear Case: A decisive rollover through SPY 768.99 that breaks support at 767.14 confirms persistent small-cap weakness, flips dealer posture toward downside exposure, and accelerates a corrective slide across the complex.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 15.3 — 15th percentile of the past year (very low vol).
SPY $769.82
Net GEX: +$647M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $768.30
Gravity (magnet): $769.83
Call Wall: $775.00 Put Wall: $760.00
Historically (this setup): resolved down 61% of the next hour · median -0.033% · n=360 across 11 sessions
Same structure, next SESSION: resolved up 60% · median +0.106% · n=40 sessions (reconstructed, 2008 on)
Expected move (this week): ±$16.60 (±2.2%)
Put/Call skew: +1.1 vol pts · roughly balanced
MM skew · 0DTE +1.1 / next +1.2 vol pts · front term structure flat
IV rank: 11 (20d) · ATM IV 7.2%
Off-exchange short volume: 51.6% · 35th pct of 120d · typical
Scheduled event: JPM reports before open on 2026-10-13 · widens the band, says nothing about direction
QQQ $749.63
Net GEX: +$598M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $748.13
Gravity (magnet): $747.27
Call Wall: $755.00 Put Wall: $736.00
Historically (this setup): resolved up 56% of the next hour · median +0.027% · n=614 across 10 sessions
Same structure, next SESSION: resolved up 52% · median +0.048% · n=522 sessions (reconstructed, 2008 on)
Expected move (this week): ±$22.39 (±3.0%)
Put/Call skew: +1.9 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +1.9 / next +2.2 vol pts · 0DTE complacency vs the next expiry
IV rank: 10 (20d) · ATM IV 10.6%
Off-exchange short volume: 61.9% · 48th pct of 120d · typical
IWM $281.69
Net GEX: +$204M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $280.17
Gravity (magnet): $282.55
Call Wall: $284.00 Put Wall: $277.00
Historically (this setup): resolved down 56% of the next hour · median -0.030% · n=562 across 6 sessions
Same structure, next SESSION: resolved down 52% · median -0.040% · n=304 sessions (reconstructed, 2008 on)
Expected move (this week): ±$8.03 (±2.9%)
Put/Call skew: +1.6 vol pts · puts bid — downside hedging demand
MM skew · 0DTE +1.6 / next +1.5 vol pts · front term structure flat
IV rank: 8 (20d) · ATM IV 10.7%
Off-exchange short volume: 61.2% · 40th pct of 120d · typical
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — while dealers hold long gamma, each session's options decay pulls their delta toward the walls: a recurring drift into the daily close (the pin) through the week. Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →