2026-10-11 · Dr. NoVo
NoVo · The Week Ahead
Structural Bias · BULLISH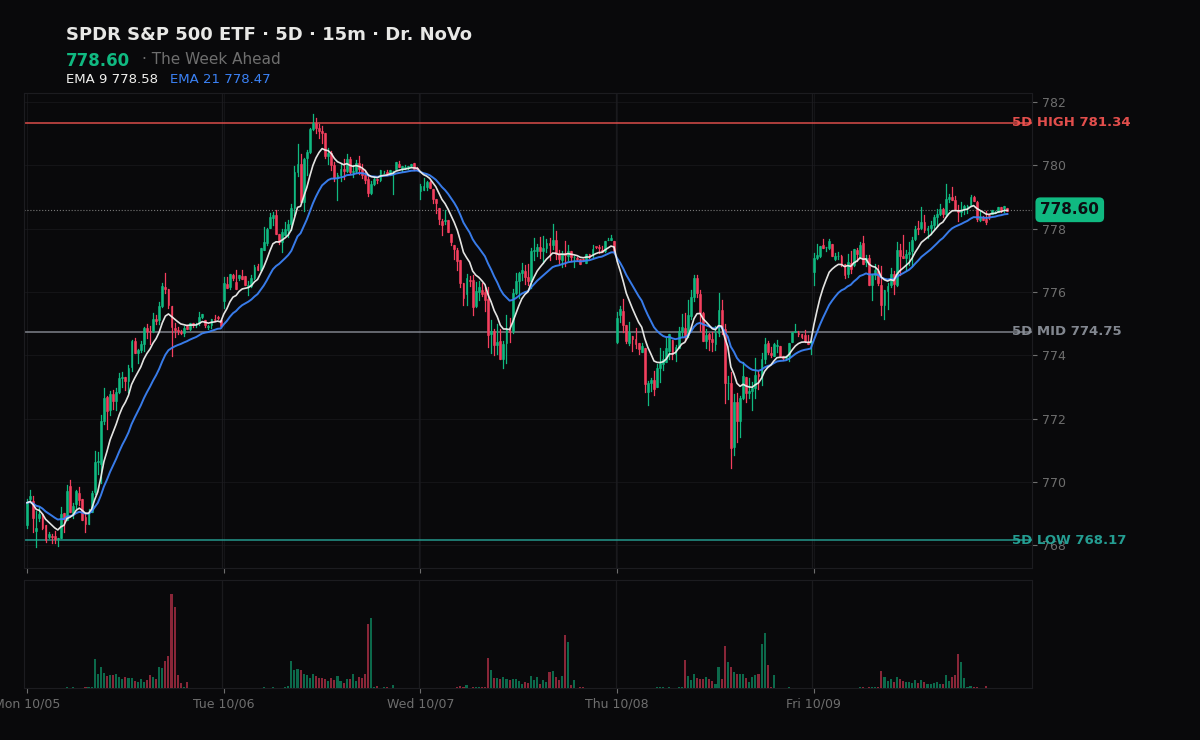
BOTTOM LINE: Equities enter the week with large caps and small caps structurally cushioned by stabilizing dealer gamma while tech remains vulnerable to accelerated extensions, leaving continuation dependent on inflation prints and Q3 earnings to justify the bid against elevated bond yields.
THE WEEK AHEAD
The index complex enters the week with a clear mechanical divergence. Across the multi-day picture, SPY sits in positive gamma where dealer hedging dampens volatility and enforces a mean-reverting grind, and IWM similarly holds a positive-gamma posture that cushions small caps against disorderly breaks. In sharp contrast, QQQ is locked in negative gamma, a regime where dealers mechanically sell into dips and buy into rips, amplifying directional swings and extending intraday trends. On Hyperliquid, weekend perps reflect a modest upward drift since Friday's cash close: the S&P 500 perp has the market +0.25% and the Nasdaq 100 perp has it +0.46%, carried by unweighted mega-cap bids led by TSLA (+0.52%), AMZN (+0.40%), MSFT (+0.35%), GOOGL (+0.31%), NVDA (+0.27%), META (+0.26%), and AAPL (+0.16%). Because there is no liquid small-cap perp, these offshore prints provide no read on IWM. Whether the week resolves into a broader breakout or stalls into distribution hinges on tech aligning with the stabilizing large-cap structure rather than pulling the complex lower through amplifying dealer mechanics.
CATALYSTS
Monday opens with equity markets active while U.S. bond markets are closed for Columbus Day and Indigenous Peoples' Day, muting Treasury rate discovery until cash fixed-income trading resumes. Tuesday shifts attention to the opening salvo of Q3 bank earnings before the bell, with reports from JPMorgan Chase (JPM), UnitedHealth Group (UNH), Goldman Sachs (GS), Wells Fargo (WFC), Citigroup (C), and Johnson & Johnson (JNJ). Wednesday brings the primary macro volatility event: the September Consumer Price Index (CPI) at 8:30 AM ET alongside Fed commentary from Governor Michelle Bowman and Richmond Fed President Thomas Barkin, followed by the Fed Beige Book at 2:00 PM ET and pre-market earnings from Bank of America (BAC), Morgan Stanley (MS), ASML Holding (ASML), and BlackRock (BLK). Thursday sustains the data load with September Retail Sales, Producer Price Index (PPI), and weekly jobless claims alongside Taiwan Semiconductor Manufacturing Co. (TSM) earnings and Fed remarks. Friday rounds out the slate with September Industrial Production and Capacity Utilization.
SCENARIOS
The base case favors a rotational grind within the weekly expected moves, where SPY tests overhead resistance at Friday's high of 779.42 but mean-reverts against its upper boundaries as positive dealer gamma absorbs extensions, provided price holds above Friday's after-hours low at 778.16 and session low at 775.14. The bull case triggers on a sustained SPY push through after-hours resistance at 779.06 and 779.42, unlocking an expansion toward the 780.00 call wall as QQQ transitions out of negative gamma and small caps confirm the advance. The bear case activates on a SPY breakdown below after-hours support at 778.16 and a clean break beneath Friday's low at 775.14; that breakdown threatens the dampening regime on SPY and exposes deeper downside toward the 770.00 put wall, particularly if accelerating dealer selling across negative-gamma QQQ drags IWM below its lower bounds.
DEALER POSITIONING MAP · SPY / QQQ / IWM
Vol environment: VIX 14.8 — 8th percentile of the past year (very low vol).
SPY $778.60
Net GEX: +$1.7B · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $776.25
Gravity (magnet): $778.70
Call Wall: $780.00 Put Wall: $770.00
Historically (this setup): resolved down 54% of the next hour · median -0.026% · n=457 across 13 sessions
Same structure, next SESSION: resolved up 55% · median +0.042% · n=437 sessions (reconstructed, 2008 on)
Expected move (this week): ±$16.28 (±2.1%)
Put/Call skew: +0.6 vol pts · roughly balanced
MM skew · 0DTE +0.6 / next +0.7 vol pts · front term structure flat
ATM IV: 5.6% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers SOLD 8.9M SPY shares (~$6.9B) 2026-10-09 final · 0DTE -8.7M · signed 100% of 9.3M contracts
QQQ $751.37
Net GEX: -$270M · negative — dealers amplify moves (moves extend)
Gamma Flip: $752.10
Gravity (magnet): $747.72
Call Wall: $755.00 Put Wall: $750.00
Historically (this setup): resolved up 51% of the next hour · median +0.015% · n=266 across 10 sessions
Same structure, next SESSION: resolved up 58% · median +0.099% · n=421 sessions (reconstructed, 2008 on)
Expected move (this week): ±$21.75 (±2.9%)
Put/Call skew: +0.9 vol pts · roughly balanced
MM skew · 0DTE +0.9 / next +1.3 vol pts · 0DTE complacency vs the next expiry
ATM IV: 8.9% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers SOLD 1.7M QQQ shares (~$1.3B) 2026-10-09 final · 0DTE -1.4M · signed 99% of 5.6M contracts
IWM $279.01
Net GEX: +$82M · positive — dealers dampen moves (grind / mean-revert)
Gamma Flip: $278.38
Gravity (magnet): $279.83
Call Wall: $281.00 Put Wall: $275.00
Historically (this setup): resolved up 66% of the next hour · median +0.052% · n=468 across 13 sessions
Same structure, next SESSION: resolved up 61% · median +0.198% · n=36 sessions (reconstructed, 2008 on)
Expected move (this week): ±$7.83 (±2.8%)
Put/Call skew: +0.1 vol pts · roughly balanced
MM skew · 0DTE +0.1 / next +0.2 vol pts · front term structure flat
ATM IV: 9.4% · quote from outside option hours, not ranked
Dealer hedging (signed options flow): dealers SOLD 937K IWM shares (~$261.3M) 2026-10-09 final · 0DTE -715K · signed 99% of 779K contracts
Gamma Flip = where dealer hedging flips from dampening to amplifying moves. Call/Put Walls = the largest call/put gamma strikes (pin / resistance above, support below). Expected move = the ±1σ range priced into at-the-money options. Public options data.
FLOW DYNAMICS
Charm — while dealers hold long gamma, each session's options decay pulls their delta toward the walls: a recurring drift into the daily close (the pin) through the week. Vanna — vol is low and dealers are long gamma; a VIX spike would flip them toward selling into weakness (amplifying) — the risk that changes the map. Second-order dealer flow context.
This read landed hours ago for subscribers.
The Open, The Close, and The Week Ahead hit your inbox before the bell — plus the live dealer dashboard.
Start a 7-day free trial →